Compare UAE credit cards side by side
147 cards from 16 UAE banks, compared on minimum salary, annual fee, rewards and FX markup — re-verified monthly.
Affiliate disclosure. Some “Apply” links below are partner links and we may earn a commission at no extra cost to you. This never influences which cards appear or how they are ranked — the comparison uses only each card’s published terms. How we make money.
Filter 147 cards by salary, bank and what you want them to do. Pin up to four to compare side by side — the comparison happens here, the application happens on the bank's own site.


One card is rarely optimal. Our Card Stack Builder reads your monthly spend mix and finds the combination of 1–5 cards that maximises your net annual rewards — after fees, caps and minimum-spend gates. It's the reason people choose YallaCalculators.
The grid above compares all 147 active UAE cards — every one now has verified card art, and the optimizer models the same set.


Independent, UAE-specific guides on cashback, stacking, travel, Islamic cards, lounges, fees and bank-by-bank comparisons. No affiliate spin.
Top cashback cards with real reward rates, caps and fees compared.
Use multiple cards strategically to maximise rewards across categories.
Up to 7% cashback on groceries. FAB Share, ADCB 365 and more.
The questions UAE residents ask most about eligibility, applying, and how we stay independent.
It allocates your monthly spend across each card's reward categories to maximise net annual value — rewards plus benefits you'll actually use, minus annual fees. Category caps, minimum-spend gates, and points devaluation are all modelled. Cards are ranked by ongoing yearly yield, not by one-off welcome bonuses, and the builder only suggests a multi-card stack when it genuinely beats the best single card for your spend.
The 'Apply now' links may be affiliate links, but they have zero influence on which cards appear or how they're ranked. The optimizer only ever sees your spending pattern and each card's published terms — it has no knowledge of which cards pay a commission. We never reorder, upweight, or insert a card because of an affiliate relationship.
Reward rates, fee caps, and salary thresholds reference each issuing bank's published terms and UAE Central Bank circulars, and are re-verified monthly. The 'Last verified' date in the Source data section shows the most recent audit. Discontinued and closed-to-new-applicant cards are excluded from new-stack recommendations.
Beyond a couple of cards, each additional card adds diminishing reward value but real management overhead — more statements, due dates, and minimum spends to track. The optimizer applies a complexity penalty of AED 200/year per card beyond the second and stops at five, so it only adds a card when the extra rewards clearly outweigh the hassle.
Most UAE cards start at AED 5,000/month for salaried applicants. Premium tiers (World, Infinite, Signature) typically need AED 15,000–50,000+. Use the salary filter to see only cards you'll actually qualify for — we never show you a card you can't get. Banks also require a valid UAE residence visa and verify income via MOHRE and Al Etihad Credit Bureau.
No. There is no introduction service behind this page: we do not send your details to a bank, broker or advisor, and nothing here triggers a phone call. The comparison and the Card Stack Builder run entirely on each card's published terms and the spending you enter yourself.
Every major UAE issuer — ADCB, Emirates NBD, FAB, RAKBANK, Mashreq, HSBC, Standard Chartered, Citibank, CBD, Dubai Islamic Bank, ADIB, Emirates Islamic, Al Hilal and more. We re-verify the data monthly, adding new cards and removing discontinued ones, and the comparison grid only shows cards with verified details and current card art — a small number of active cards are held back until we have their art.
No. The optimizer only sees your spending and each card's published terms — it has no commission field, so no bank can buy a position. Where an "Apply" link to a bank's own site earns us anything, that is set out on our affiliate disclosure page.
| Card |
|---|
| Min salary |
| Annual fee |
| Interest rate |
| Key rewards |
| FX markup |
| Welcome bonus |
Ten UAE credit cards on the six facts that decide which one you should hold: what you have to earn to be approved, what the card costs a year, what it charges on a balance, what it actually returns, what it adds to every non-AED transaction, and what it pays you to sign up. Thresholds across the full comparison start at AED 4,500 a month, and 51 cards are open at AED 5,000 or below. Pin any two to four cards in the grid above for the same six facts on the cards you choose.
| Card | Min salary | Annual fee | Interest rate | Key rewards | FX markup | Welcome bonus |
|---|---|---|---|---|---|---|
| Emirates IslamicEmirates Islamic Etihad Guest Premium Credit Card | AED 4,500/mo | AED 2,625/yr | Profit-rate based | 1.43% back in miles on flights | 2.34% | up to 55,000 Etihad Guest Miles (AMF options AED 1,500 → 25,000 Miles; AED 2,500 → 55,000 Miles); separate promo offers up to 100,000 bonus Miles |
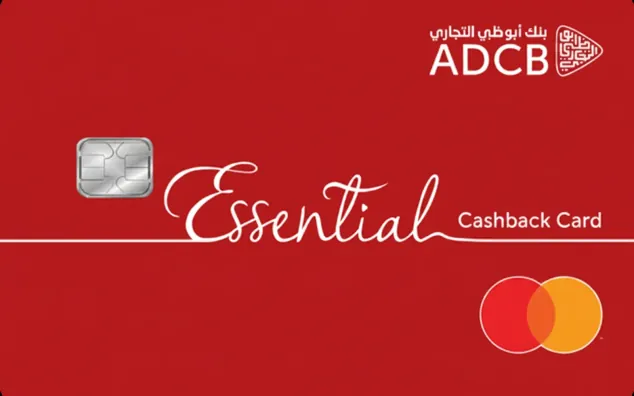
| ADCBADCB Essential Cashback Credit Card | AED 5,000/mo | Free for life | 3.25% / mo | 1% cashback on all other spend | 2.99% | Up to AED 350 welcome cashback on digital channels (promotional) |
| ADIBADIB Smiles Classic Card | AED 5,000/mo | Free for life | Profit-rate based | 1.5% back in points on all other spend | 2.99% | 5,000 Smiles welcome points |
| CitiCiti Simplicity Credit Card | AED 5,000/mo | Free for life | 3.50% / mo | Not published | 2.99% | Not published |
| DIBDIB Prime Gold Card | AED 5,000/mo | Free for life | Profit-rate based | 0.3% back in points on all other spend | 3.14% | Not published |
| ENBDEmirates NBD Go4it Gold Credit Card | AED 5,000/mo | Free for life | 3.25% / mo | 1% back in points on utilities | 1.99% | Not published |
| FABFAB du Credit Card | AED 5,000/mo | Free for life | 3.99% / mo | 0.3% back in points on all other spend | 2.61% | Not published |
| MashreqMashreq Al Islami Cashback Credit Card | AED 5,000/mo | Free for life | Profit-rate based | 5% cashback on dining | 2.89% | AED 500 for new customers on AED 5000 spend in first 2 months |
| RAKBANKRAKBANK RED Credit Card | AED 5,000/mo | Free for life | 3.25% / mo | 1.5% cashback on all other spend | 2.99% | Not published |
| HSBCLive+ Cashback Credit Card | AED 5,000/mo | AED 314/yr — first year free | 3.49% / mo | 6% cashback on dining | 3.5% | Not published |
Every card’s reward rates, fee caps and salary thresholds reference each issuing bank’s published terms and UAE Central Bank circulars, cross-checked against the relevant official regulators — RERA and DLD for property, MOHRE for labour and eligibility, DHA and KHDA for healthcare and education perks, and ICP for residency rules. Discontinued and closed-to-new-applicant cards are excluded from new-stack recommendations. This is a comparison tool, not financial advice.
Picking the right card in the UAE comes down to four things: whether you meet the bank’s salary requirement, how you actually spend, the fees you will really pay, and whether you need a Sharia-compliant option. Getting these right matters more than chasing the biggest headline reward rate.
Salary & eligibility. Most UAE banks set a minimum monthly salary — typically around AED 5,000 for entry-level cards, rising to AED 15,000–25,000+ for premium World, Signature and Infinite tiers. Banks verify income and check your record with the Al Etihad Credit Bureau (AECB), and your existing repayments feed a Debt Burden Ratio that the UAE Central Bank caps at 50% of income — so card and loan repayments together cannot exceed half your salary. Filter by your salary band first; there is no value in applying for a card you cannot be approved for.
Match rewards to your spend. Cashback cards return a flat or category rate (groceries, dining, fuel, utilities) to your statement — best when you want simple, predictable value. Air-miles cards earn Skywards, Etihad Guest or similar and suit frequent flyers, but miles can be devalued and only pay off if you fly often. Rewards-points cards sit in between. Use the Card Stack Builder to model your real monthly spend across categories and see the net annual value of one card — or a stack — after fees and caps.
Watch the fees. The headline is the annual fee, but many UAE cards waive it above a yearly spend threshold, or are free-for-life. The cost most people overlook is the foreign-currency (FX) markup — typically 1.99%–2.99% added to every non-AED transaction, including overseas travel and international online shopping. If you spend abroad often, a low- or zero-FX card can save more than the cashback on a domestic card.
Islamic (covered) cards. Sharia-compliant cards replace interest with a transparent profit-rate or fixed-fee model and avoid non-compliant merchant categories, while still offering rewards, lounge access and instalment plans. If Sharia compliance matters to you, compare covered cards on their monthly profit rate and fee schedule rather than a conventional APR.
Choosing a bank before a card? Compare account strength, card line-ups, digital apps and branch reach across the major issuers in our UAE bank comparison hub, then come back here to pick the card.
Opens your browser’s print dialog — choose “Save as PDF” to keep this page and your figures.